Liberia is staking its economic future on a sweeping wave of mining and energy agreements aimed at unlocking up to US$4.8 billion in foreign investment under President Joseph Nyuma Boakai. Framed as both an economic strategy and a defining political gamble, the investment drive is designed to finance the country’s US$8 billion ARREST Agenda for Inclusive Development (AAID) through 2029, at a scale domestic revenues alone cannot sustain.
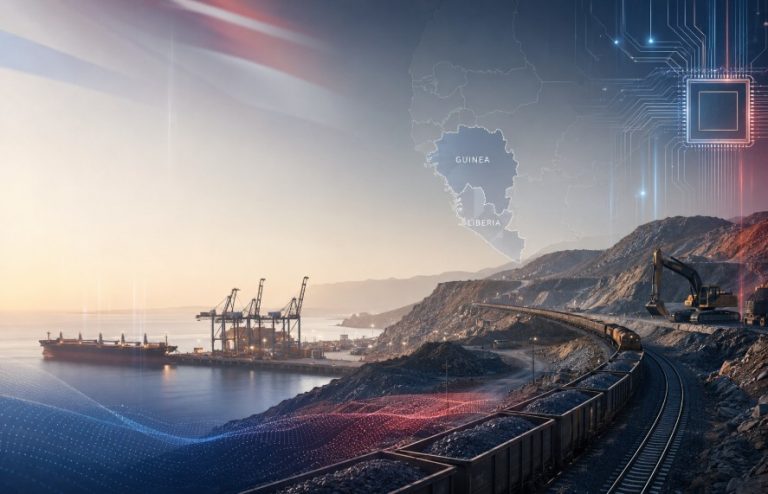
Nearly US$4 billion of the projected inflows is tied to mining and infrastructure, led by expansions from ArcelorMittal and rail access agreements with Ivanhoe Atlantic Inc.. ArcelorMittal plans to raise iron ore exports from roughly 8 million to nearly 20 million metric tons annually, backed by a new concentrator, rail upgrades, and port improvements. Ivanhoe Atlantic’s agreement to move Guinean ore through Liberian infrastructure further positions the country as a regional mineral transit hub.
An additional US$800 million is anticipated in offshore energy, following eight petroleum agreements split between TotalEnergies and Oranto Petroleum, covering multiple blocks in the Liberian Basin. The Oranto deals include a US$12 million signature bonus and potential investments of up to US$200 million per block, with further interest reportedly emerging from a major U.S. oil company.
The administration argues that renewed diplomacy, policy stability, and Liberia’s election to the UN Security Council (2026–2027) have helped restore investor confidence after years of stalled concessions and skepticism. Ultimately, the success of these agreements will determine whether foreign capital can translate into infrastructure, jobs, and revenue growth — and shape both the fate of the AAID and Boakai’s political prospects heading into 2029.